TH
 EN
Planning Your Chiang Mai Real Estate Portfolio for the Next 10 Years — From 1 Unit to Financial Freedom
This article lays out a genuine roadmap with real numbers for building a Chiang Mai real estate portfolio over 10 years.
Base Assumptions
Starting capital: THB 700,000 (for first property down payment); Monthly income: THB 80,000 (still employed); Annual property price appreciation: 5%; Annual rental rate increase: 3%.
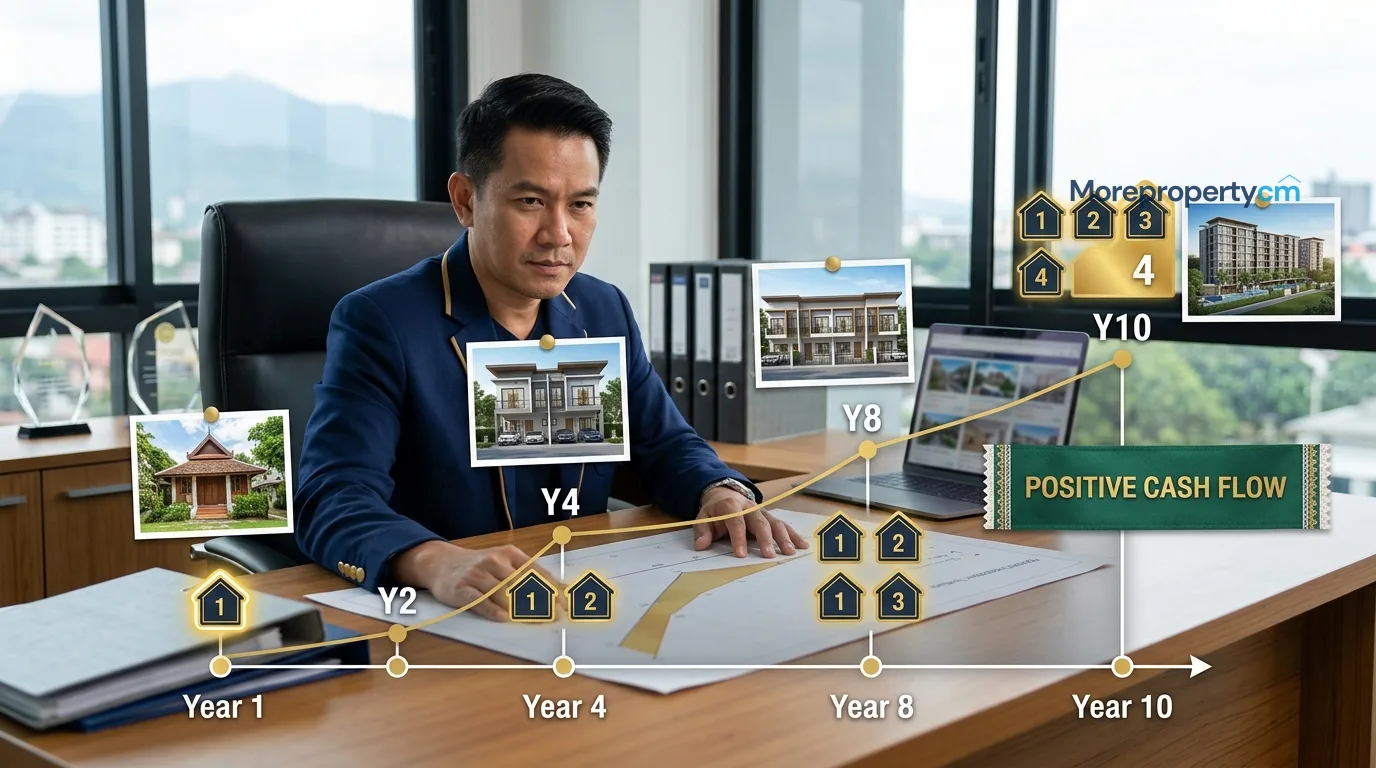
Years 1-2: First Property
Buy: 1-bedroom condo near CMU area, THB 2,200,000. Down 30%: THB 660,000; Borrow THB 1,540,000; Repayment over 20 years @6%: THB 11,000/month. Rent: THB 9,500/month. After all costs: approximately -THB 3,500/month (negative Cash Flow — acceptable while employed).
Years 3-4: Accumulate Capital, Buy Second Property
First property has appreciated (Year 4 ≈ THB 2,700,000). Use Equity to purchase second property.
Property 2: Studio in Nimman, THB 1,500,000. Down 20%: THB 300,000; repayment: THB 8,600/month; rent: THB 7,500/month.
Years 5-6: 2-Unit Portfolio Approaching Break Even
Property 1 rent adjusted to THB 10,400/month; Property 2 rent THB 8,200/month. Total rent: THB 18,600/month; total mortgage: THB 19,600/month. Combined Cash Flow: -THB 1,000/month (near Break Even).
Years 7-8: Third Property
Use Capital Gain or Refinance from Property 1; buy Property 3 or Flip one property to increase capital.
Years 9-10: 3-4 Unit Portfolio, Positive Cash Flow
With 3-4 units, continuously rising rents, and meaningful loan principal already repaid, combined Cash Flow turns positive. Expected Net Passive Income Year 10: THB 15,000-30,000/month.
Key Success Factors
1. Patience — never consume rental income; always reinvest. 2. Choose good-location, stable-Demand properties — not cheapest. 3. Keep your main job in early years to support negative Cash Flow. 4. Review the plan annually against actual market conditions.
MORE Value. MORE Trust. Always.
Contact us today for a free consultation:
Line: @morecm | www.morepropertycm.co.th
Aurakanya: +66 83-236-9428
Eknarin: +66 96-236-9745
Planning Your Chiang Mai Real Estate Portfolio for the Next 10 Years — From 1 Unit to Financial Freedom
12 Oct 2026
17 ครั้ง