TH
 EN
Preparing for Your First Home Loan — What to Do in the 12 Months Before You Apply
Applying for a home loan doesn't begin when you submit documents — it begins with preparation 1+ year in advance.
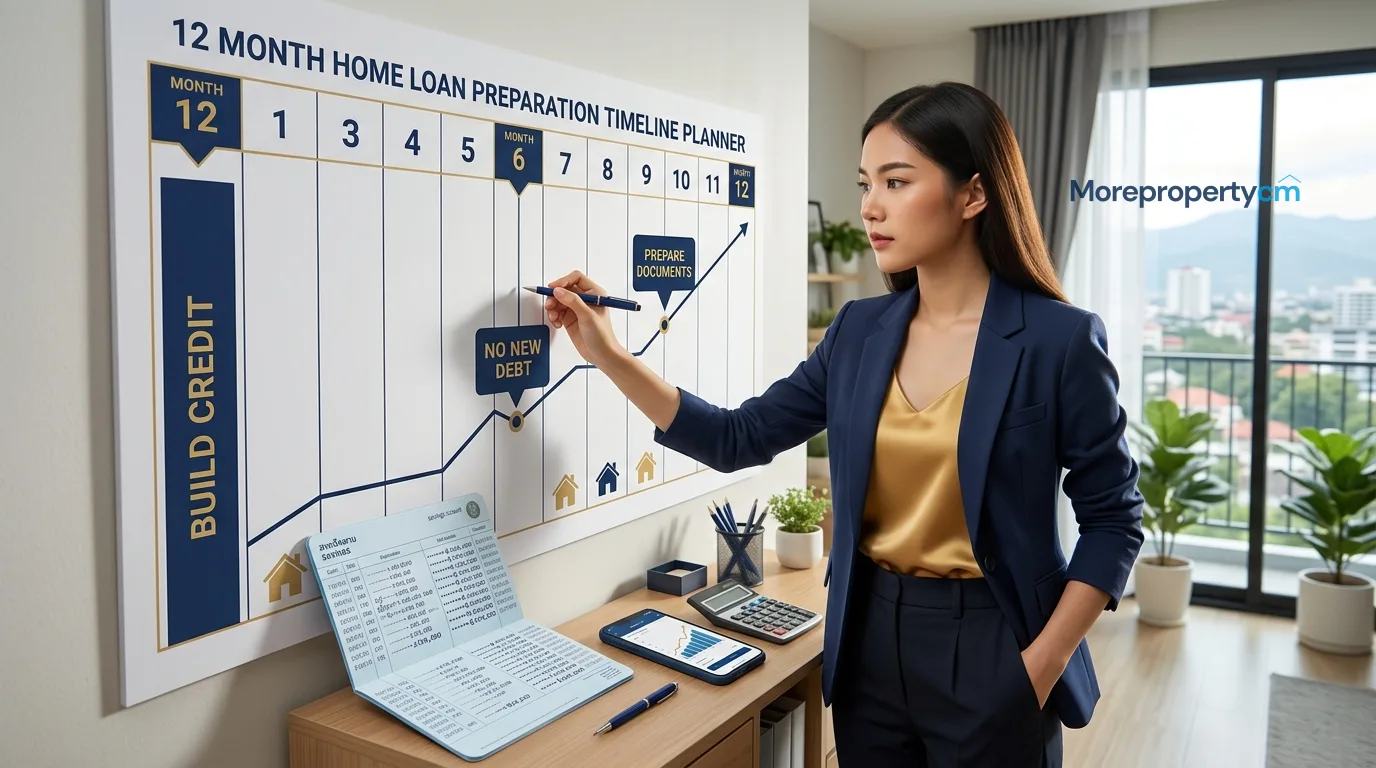
12 Months Before: Build the Foundation
Build good credit history: If you don't have a credit card, apply for one and use it responsibly — pay in full monthly, never exceed 30% of the limit
Reduce existing debt: Banks' DTI (Debt-to-Income Ratio) threshold is 40-45% of income total; high credit card or personal loan balances must come down
Start seriously saving for down payment and transfer costs: Target 20-30% of intended purchase price plus approximately 3-5% for transfer costs; save in a savings account with consistent transaction history
6 Months Before: Adjust Financial Behavior
Don't change jobs (if employed): Banks require stable income evidence — new employees still in probation are frequently declined
Don't apply for any new credit: Credit applications create Hard Inquiries in your credit record, negatively affecting short-term credit scoring
Maintain bank statements showing consistent income: Banks review the last 6-12 months; consistent income without unusual large withdrawals is critical
Never take cash advances on credit cards: Banks view this negatively as a cash flow distress signal
3 Months Before: Prepare Documents
Gather all required documentation; verify names match across all documents; compare interest rates from at least 3-5 banks
The Week Before Applying
Check your Credit Score if possible and correct any errors in your credit report; organize documents neatly
Factors That Most Affect Approval
Monthly income and consistency; debt repayment history (most critical); current DTI; employment duration; down payment available (larger down payment = easier approval and better interest rate)
MORE Value. MORE Trust. Always.
Contact us today for a free consultation:
Line: @morecm | www.morepropertycm.co.th
Aurakanya: +66 83-236-9428
Eknarin: +66 96-236-9745
Preparing for Your First Home Loan — What to Do in the 12 Months Before You Apply
25 Aug 2026
124 ครั้ง